The Cash Is Already Inside Your Business
Published September 25, 2026
How Poor Working-Capital Management Forces Nigerian Companies to Borrow at 30%+
By Joe Adinma, FCA, FCTI
Managing Partner, Joe Adinma & Co. (Chartered Accountants)
A Nigerian company approaches its bank for a ₦300 million working-capital facility. Sales are growing, suppliers need to be paid, customers have not paid, inventory must be replenished and salaries are due. The bank is willing to lend — but at an effective cost above 30%.
Management may see the facility as unavoidable. But before the loan application is signed, one harder question should be asked:
Does the company genuinely need another ₦300 million — or is a large part of that money already trapped somewhere inside the business?
Perhaps customers given 30-day credit routinely pay after 90 or 120 days. Perhaps the warehouse contains far more stock than the business economically needs. Perhaps salespeople are rewarded for invoices raised rather than cash collected. Perhaps suppliers are paid faster than necessary while customers receive generous credit without paying for it.
If so, the problem may not simply be a shortage of finance. It may be a circulation problem. And when money costs more than 30%, poor working-capital management becomes extraordinarily expensive.
Nigeria's Working-Capital Problem Is Now a Cost-of-Capital Problem
Nigerian manufacturers paid an average interest rate of about 32.1% on bank borrowing in 2025, according to Manufacturers Association of Nigeria data reported in September 2026. At that price, every unnecessary day that cash remains trapped in receivables or inventory carries a meaningful economic cost.
MAN also reported unsold manufacturing inventory of about ₦1.04 trillion in the first half of 2025, up from approximately ₦896.2 billion in the second half of 2024. Not every naira of inventory is excessive: businesses need raw materials, work in progress, finished goods and sometimes strategic buffers. But inventory is still capital, and capital that sits longer than economically necessary has a cost.
The financing constraint is wider among smaller businesses. In December 2025, the World Bank said fewer than one in twenty Nigerian MSMEs had access to bank credit, while available loans were often short-term, costly and constrained by collateral requirements.
Before asking where the next loan will come from, management should first ask where the company's existing cash has gone.
Working Capital Is Invested Capital
Working capital is often treated as an accounting calculation performed after year-end. That is a mistake. For an operating business, it is money committed to keeping the commercial engine running.
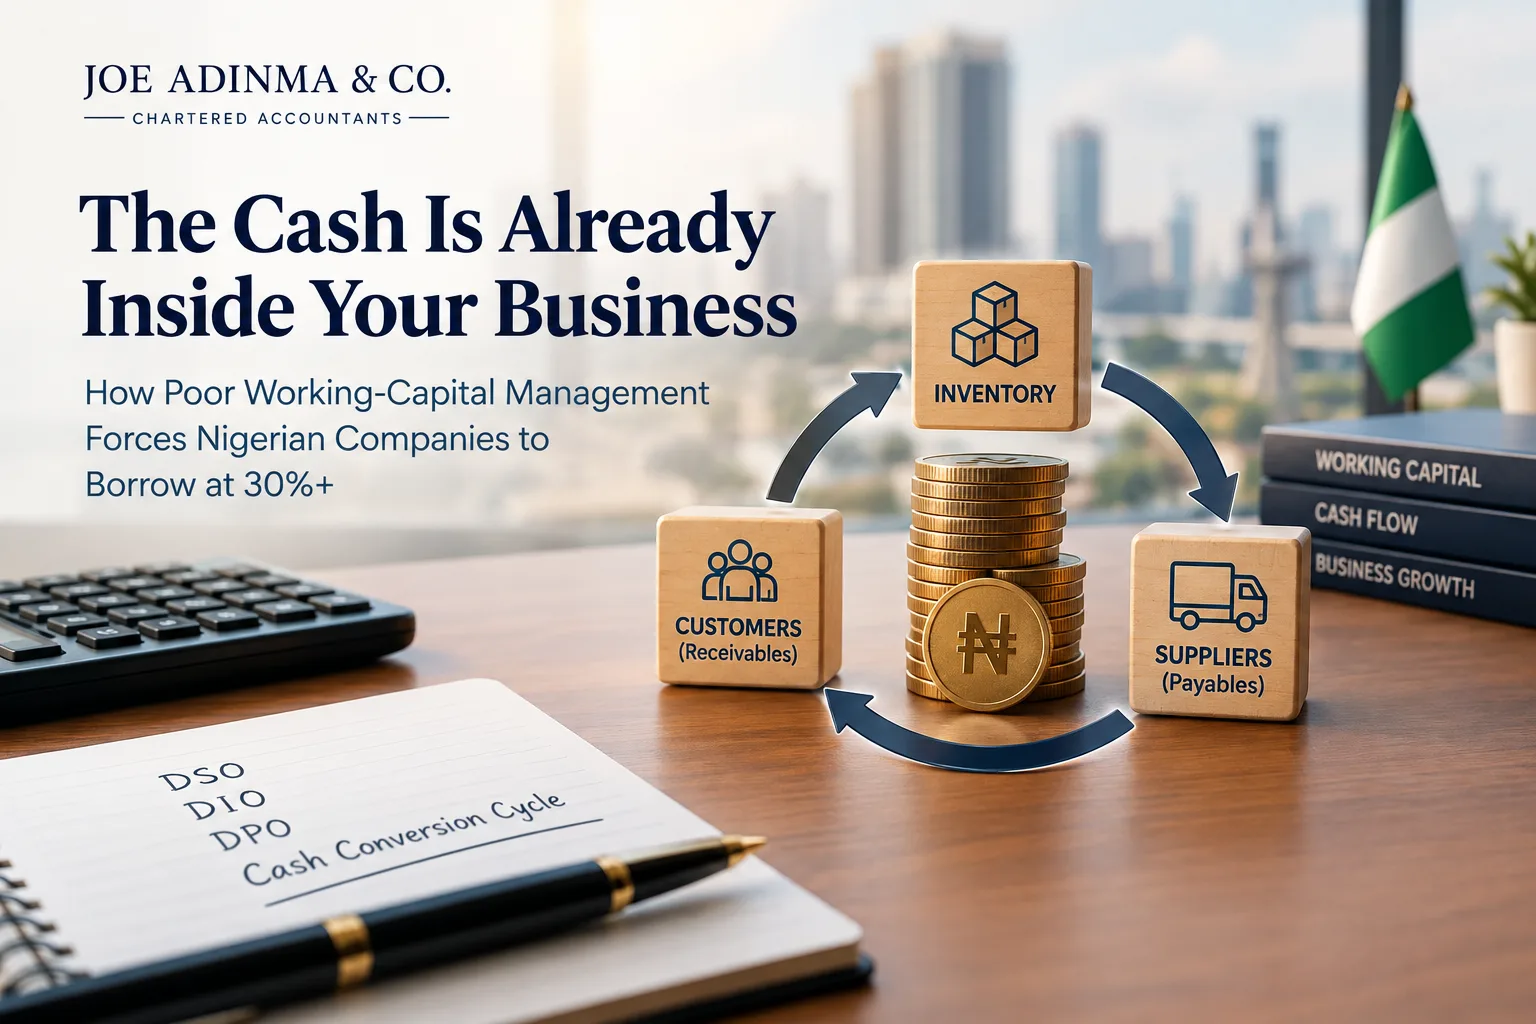
In simplified form, operating working capital is receivables plus inventory less trade payables. Receivables are money customers owe you. Inventory is money committed to goods that have not yet completed the journey back into cash. Payables are financing temporarily provided by suppliers.
The goal is not to minimise working capital indiscriminately. Too little stock can cause production interruptions and lost sales. Excessively tight credit can drive away good customers. Stretching suppliers can damage relationships and disrupt supply.
The objective is not to minimise working capital. It is to maximise the return earned on every naira committed to working capital.
Know the Three Numbers: DSO, DIO and DPO
Three standard measures help management understand how capital moves through the operating cycle. Days Sales Outstanding (DSO) measures how long customers take to pay. Days Inventory Outstanding (DIO) measures how long inventory remains in the business before sale or use. Days Payables Outstanding (DPO) measures how long the company takes to pay suppliers.
The cash conversion cycle is then expressed as: DIO + DSO − DPO.
Suppose a company holds inventory for 75 days, collects customers after 90 days and pays suppliers after 30 days. Its cash conversion cycle is 135 days. The business may therefore have to finance roughly 135 days between committing cash to operations and recovering it from customers.
Reduce that cycle from 135 days to 90 days and 45 days of financing requirement may be removed. At borrowing costs above 30%, that can be a major capital-allocation event.
Your Customers May Be Borrowing From You for Free
Consider a company with ₦300 million of average trade receivables. If those receivables are effectively supported by a financing pool costing about 32%, the simplified annual financing exposure associated with that amount is ₦96 million.
This does not mean every naira of the ₦96 million can mechanically be charged to customers, nor that all receivables are directly bank-financed. It means something commercially important: customer credit has a cost.
If a customer owes you ₦50 million for 120 days, you have effectively provided that customer with four months of financing. If your own money costs more than 30%, why should that financing automatically be free?
Your customers may be borrowing from you for free while you borrow from the bank at 32%.
Gross Margin Can Hide Bad Customer Economics
A customer may appear attractive because management sees ₦500 million of revenue and ₦100 million of gross profit. But suppose the same customer routinely pays after 120 days, disputes invoices, requires stock to be held specifically for it and creates significant collection effort and bad-debt risk.
That relationship is consuming more than product cost. It is consuming capital.
Customer profitability should therefore be examined after considering credit period, collection experience, inventory commitment, concentration risk and the financing burden created by the relationship. A high-revenue customer can still be a poor user of capital.
Salespeople Should Not Be Rewarded for Creating Receivables
A common incentive problem is simple: sales is rewarded for revenue while finance is responsible for collection. That can encourage the wrong behaviour.
A salesperson can meet a sales target by giving generous credit to customers who would not buy on stricter terms. Revenue rises, bonuses are earned, receivables grow, finance starts chasing payment and the company borrows to pay suppliers. Eventually interest expense and bad debts reveal that part of the celebrated growth was actually financed customer credit.
Commercial performance measures should therefore include cash quality — not only invoicing. Collections against sales, DSO, overdue balances, customer payment behaviour and margin after financing cost can all form part of the picture.
Credit Terms Are a Pricing Decision
Suppose two customers each buy goods worth ₦100 million. Customer A pays immediately. Customer B pays after 120 days. If both are charged exactly the same price, are they really receiving the same commercial package? No. Customer B receives both the product and approximately four months of financing.
In a low-interest-rate environment, businesses sometimes ignore that financing element. At borrowing costs above 30%, it becomes much harder to justify. A customer asking for 90 or 120 days is effectively asking: “Will you finance part of my business?” The answer may still be yes — but it should be a conscious pricing and capital-allocation decision.
Every Extra Day Has a Naira Value
Assume annual credit sales of ₦3.65 billion. That is approximately ₦10 million per day. If average collection time increases by 20 days, roughly ₦200 million of additional capital may become tied up in receivables, all else equal.
At an illustrative financing cost of 32%, financing ₦200 million for a full year represents about ₦64 million of annual financing exposure. Twenty days can therefore have a very large naira value.
Boards should not look only at the receivables balance. They should ask how many days the company is financing its customers, what one day is worth in naira and whether the return from that credit justifies the capital committed.
Inventory Is Cash Wearing Work Clothes
Inventory can create an illusion because it appears as an asset. But the business may already have paid for raw materials, freight, import duties, clearing, storage, insurance and handling. Until the stock is sold and the customer pays, the cash has not completed its journey home.
The objective is not minimum inventory; it is economically optimal inventory. Management should distinguish fast-moving stock from slow-moving, obsolete, speculative and strategic stock. It should know what each category is doing to cash and margin.
Suppose a company carries ₦400 million of inventory and analysis shows that ₦100 million is genuinely unnecessary or slow-moving. If that excess is effectively financed at 32%, its simplified financing exposure alone is about ₦32 million per annum — before warehousing, insurance, deterioration, theft, expiry, markdowns and opportunity cost.
A warehouse can look full while the bank account looks empty because they may contain the same money in different forms.
Cheap Purchasing Can Become Expensive Working Capital
Procurement should not be judged solely on the lowest unit price. Buying six months of stock to obtain a 5% bulk discount may be a poor bargain if the company then finances that stock at more than 30% and carries obsolescence risk.
Purchasing decisions should therefore consider total economics: price, quantity, holding period, financing cost, storage, spoilage, supply reliability and expected demand.
Growth Can Consume Cash Faster Than It Creates Profit
Consider an illustrative company. In Year 1, revenue is ₦1.50 billion, DSO is 45 days, DIO is 50 days and DPO is 30 days. The cash conversion cycle is therefore 65 days.
In Year 2, revenue rises to ₦2.20 billion — a 47% increase. But DSO deteriorates from 45 to 92 days, DIO from 50 to 83 days, while DPO remains 30 days. The cash conversion cycle moves from 65 days to 145 days.
Revenue has grown sharply, but the company now has to finance approximately 80 additional days of its operating cycle on a much larger revenue base. That can absorb hundreds of millions of naira.
The correct question is therefore not simply whether growth created a working-capital requirement. Management should separate the requirement caused by genuine growth from the requirement caused by weaker collection, excess inventory or poor supplier-term management. The first may justify financing. The second may require management action.
Inflation Can Increase Working Capital Merely to Stand Still
If a company historically needed ₦200 million of inventory to maintain normal operations and replacement costs rise substantially, exactly the same physical stock may now require ₦260 million. Nothing operationally has improved; more naira are simply needed to finance the same quantity.
Receivables behave similarly. Higher selling prices increase invoice values. Even if DSO remains unchanged, more cash becomes tied up. That helps explain why a business can report strong revenue growth while its liquidity position becomes more strained.
A Genuine Receivable Can Still Cripple the Company Waiting to Collect It
In June 2026, the Federal Ministry of Finance announced approval of payments to more than 1,240 local contractors after verification and reconciliation of outstanding obligations. The Ministry explicitly described the payments as providing liquidity to help businesses return to sites, pay workers, settle suppliers and meet commitments.
The lesson is broader than government contracting. A receivable can be valid, properly invoiced and ultimately recoverable — and still create severe liquidity pressure while the company waits.
Before accepting a contract, management should therefore ask not only “What is the margin?” but also “How much cash must we commit, and how long before we recover it?”
Suppliers Are Part of the Financing Structure
Trade payables are not merely bills waiting to be paid. Supplier credit can be an important source of operating finance.
If suppliers allow 60 days while customers pay in 30, the cash cycle is fundamentally different from one where suppliers demand cash immediately and customers pay in 90 days. But indiscriminately delaying suppliers is not a strategy: it can destroy trust, remove discounts, increase prices and disrupt supply.
The objective is deliberate alignment of supplier terms with the company's operating cycle.
Working Capital Is a Cross-Functional Management Issue
Finance cannot solve working capital alone. Sales determines customers, prices and credit terms. Procurement determines buying quantities and negotiates supplier terms. Operations influences production cycles, wastage and stock. Logistics affects delivery and invoicing speed. Finance monitors collection, payment, cash and funding. Management sets incentives and resolves the trade-offs.
If sales gives 120-day credit, procurement buys six months of stock and finance is instructed to pay suppliers in 14 days, no treasury manager can magically eliminate the resulting cash gap. The problem was created before finance received the invoice.
Borrowing Should Finance an Efficient Cycle — Not Hide an Inefficient One
Debt can be entirely appropriate for working capital. A distributor may borrow ₦100 million, purchase fast-moving goods, sell them quickly, collect, repay the facility and repeat the cycle profitably.
The problem arises when debt becomes a substitute for management discipline. If receivable days increase every year, inventory keeps accumulating and overdrafts keep rising, another loan may simply postpone the real problem.
Poor working-capital management causes a cash shortage; the shortage creates borrowing; borrowing creates interest; interest weakens cash generation; and the business borrows again.
A company may think it has a banking problem when it actually has an operating problem.
The Working-Capital Release Test
Management should translate operational improvements into cash. The following is a simplified illustration, not a forecast for any particular company.
Management action | Current → target | Assumption | Approx. cash release |
Reduce receivable days | 60 → 55 days | ₦7.3bn annual credit sales; ~₦20m/day | ₦100m |
Reduce inventory days | 70 → 60 days | ₦4.38bn annual cost of sales; ~₦12m/day | ₦120m |
Improve supplier terms | 30 → 35 days | ₦4.38bn annual purchases/cost base proxy; ~₦12m/day | ₦60m |
Potential cash release | ₦280m | ||
Illustrative example only. Actual cash release depends on the company's sales mix, cost base, VAT/tax effects, seasonality, customer behaviour, inventory composition, supplier terms and other operating factors.
Management preparing to borrow ₦300 million might therefore discover that a large part of the requirement can be met by releasing cash already tied up in the cycle. Not every company will have that opportunity, but it should be quantified before expensive external money is raised.
Alternative Financing Can Help — But It Must Fit the Transaction
In April 2026, IFC and Standard Chartered announced a risk-sharing facility covering up to $300 million of supply-chain and trade-finance assets across eight African markets, including Nigeria. The programme includes instruments such as payables finance, receivables discounting and pre-shipment finance.
The broader lesson is that overdrafts are not the only answer. Depending on circumstances, businesses may consider invoice discounting, factoring, supply-chain finance, customer advances, supplier credit, distributor finance, purchase-order finance or appropriately structured trade facilities.
Financing should follow the commercial transaction. But financing a receivable does not make a bad customer good. Credit assessment, ageing, concentration limits, dispute resolution and collection discipline remain essential.
IFRS 9 Adds a Reporting Discipline to the Commercial Reality
From a financial-reporting perspective, IFRS 9 requires expected credit losses to be recognised on relevant financial assets, including trade receivables. The standard therefore reinforces a commercial truth: an invoice is not automatically worth its face value merely because it exists.
Credit risk begins when the receivable is created. Management should not finance weak credit faster; it should improve the credit decision.
The Working-Capital Dashboard Every CEO Should See
Monthly management reporting should show DSO, DIO, DPO and the cash conversion cycle, together with the naira value of adverse movement. It should also show receivables ageing, overdue and disputed balances, top debtors, collections against target, inventory ageing, slow-moving and obsolete stock, supplier ageing, critical overdue suppliers, overdraft utilisation, effective borrowing cost and covenant headroom.
Most importantly, every material adverse variance should have an owner, an action and a deadline. A dashboard that merely reports deterioration is not management.
The Joe Adinma & Co. Working-Capital Challenge
Before approving another working-capital facility, management should be able to answer all ten of these:
1. How much cash is tied up in receivables, and how much is overdue?
2. What are our DSO, DIO and DPO trends, and what caused the movement?
3. Which customers consume the most working capital, not merely generate the most revenue?
4. Are credit terms reflected in pricing and customer profitability?
5. How much inventory is genuinely required, and how much is slow-moving, obsolete or speculative?
6. Are supplier terms being fully and responsibly utilised?
7. What is our cash conversion cycle, and what is one day of that cycle worth in naira?
8. How much cash can realistically be released in 30, 60 and 90 days?
9. Is the proposed borrowing funding growth — or funding inefficiency?
10. If we fix the working-capital problem, how much less would we need to borrow?
That may be the most valuable question of all.
Sometimes the Cheapest Bank Facility Is the One You No Longer Need
A company that believes it needs ₦300 million may have more than one route. It can borrow the full amount at more than 30%, or it may be able to collect overdue debtors, release excess inventory, negotiate better supplier terms and borrow only the residual requirement.
The second route will not always be available. But it should be investigated before the first is treated as inevitable.
The purpose of working-capital management is not to eliminate borrowing. It is to ensure the company borrows because sound economics require capital — not because management has lost control of the capital already inside the business.
Final Thought
Nigeria undoubtedly has a financing problem. Credit remains difficult to access for many businesses and, when available, can be extremely expensive. That deserves serious policy attention.
But businesses cannot wait for the financial system to become cheaper before improving their own capital efficiency. At borrowing costs above 30%, every unnecessary day in receivables matters. Every unnecessary day of inventory matters. Every poorly structured credit term matters. Every sales incentive that rewards invoicing while ignoring collection matters.
Before management tells the board, “We need another ₦300 million working-capital facility,” the board should ask a different question:
How much cash can we release from the business before we borrow one more naira?
Sometimes the cash is sitting in the customer's account. Sometimes it is sitting in the warehouse. Sometimes it is trapped in an inefficient operating cycle while the business pays the bank more than 30% to replace it.
Some companies do not have a shortage of capital. They have a circulation problem.
How an Independent Working-Capital Review Can Help
A structured working-capital review can help management analyse receivables, inventory, supplier terms, cash-conversion cycles, customer and product economics, cash-flow forecasts and financing requirements.
It can also help quantify what each day of the operating cycle costs, distinguish genuine growth financing from operational inefficiency, identify realistic cash-release opportunities and determine how much external capital the business actually needs.
Before raising expensive external capital, it may be worth finding out how much capital is already available inside the business.
About the Author
Joe Adinma, FCA, FCTI, is the Managing Partner of Joe Adinma & Co. (Chartered Accountants). He advises businesses on financial reporting, audit, taxation, governance, financial management and strategic financial decision-making.
Disclaimer: This article is intended for general information and educational purposes. It does not constitute investment, tax, legal, credit or financing advice. Working-capital and financing decisions should be evaluated based on the specific commercial circumstances, risks, contractual terms and financial position of each business.
Selected Sources and Technical References
• Manufacturers Association of Nigeria (MAN), as reported by Punch, 2 September 2026, “Manufacturers pay 32% interest on loans amid easing.”
• Manufacturers Association of Nigeria manufacturing performance data, as reported by The Guardian, including unsold inventory of approximately ₦1.04 trillion in H1 2025 versus ₦896.2 billion in H2 2024.
• World Bank, 22 December 2025, “World Bank Approves $500 Million to Expand Finance for Small Businesses in Nigeria.” https://www.worldbank.org/en/news/press-release/2025/12/22/world-bank-approves-500-million-to-expand-finance-for-small-businesses-in-nigeria
• Federal Ministry of Finance, 2026, “Federal Ministry of Finance Approves Payments to 1,240 Local Contractors.”
• International Finance Corporation (IFC), 2026, “IFC and Standard Chartered Partner on Supply Chain Finance to Support African Businesses.” https://www.ifc.org/en/pressroom/2026/ifc-and-standard-chartered-partner-on-supply-chain-finance-to-support-african-busi
• IFRS Foundation, IFRS 9 Financial Instruments — impairment requirements and expected credit losses for financial assets, including trade receivables. https://www.ifrs.org/issued-standards/list-of-standards/ifrs-9-financial-instruments/